Mortgage Applications Rise 3.4% as MBA's 30-Year Rate Slips to 7.37%
MBA says applications rose 3.4% in the week ended Oct. 23 as its 30-year conforming rate fell to 7.37%. Purchase applications remain 18% below last year and refinances 61% lower.
By Christopher Salem · 4 min read
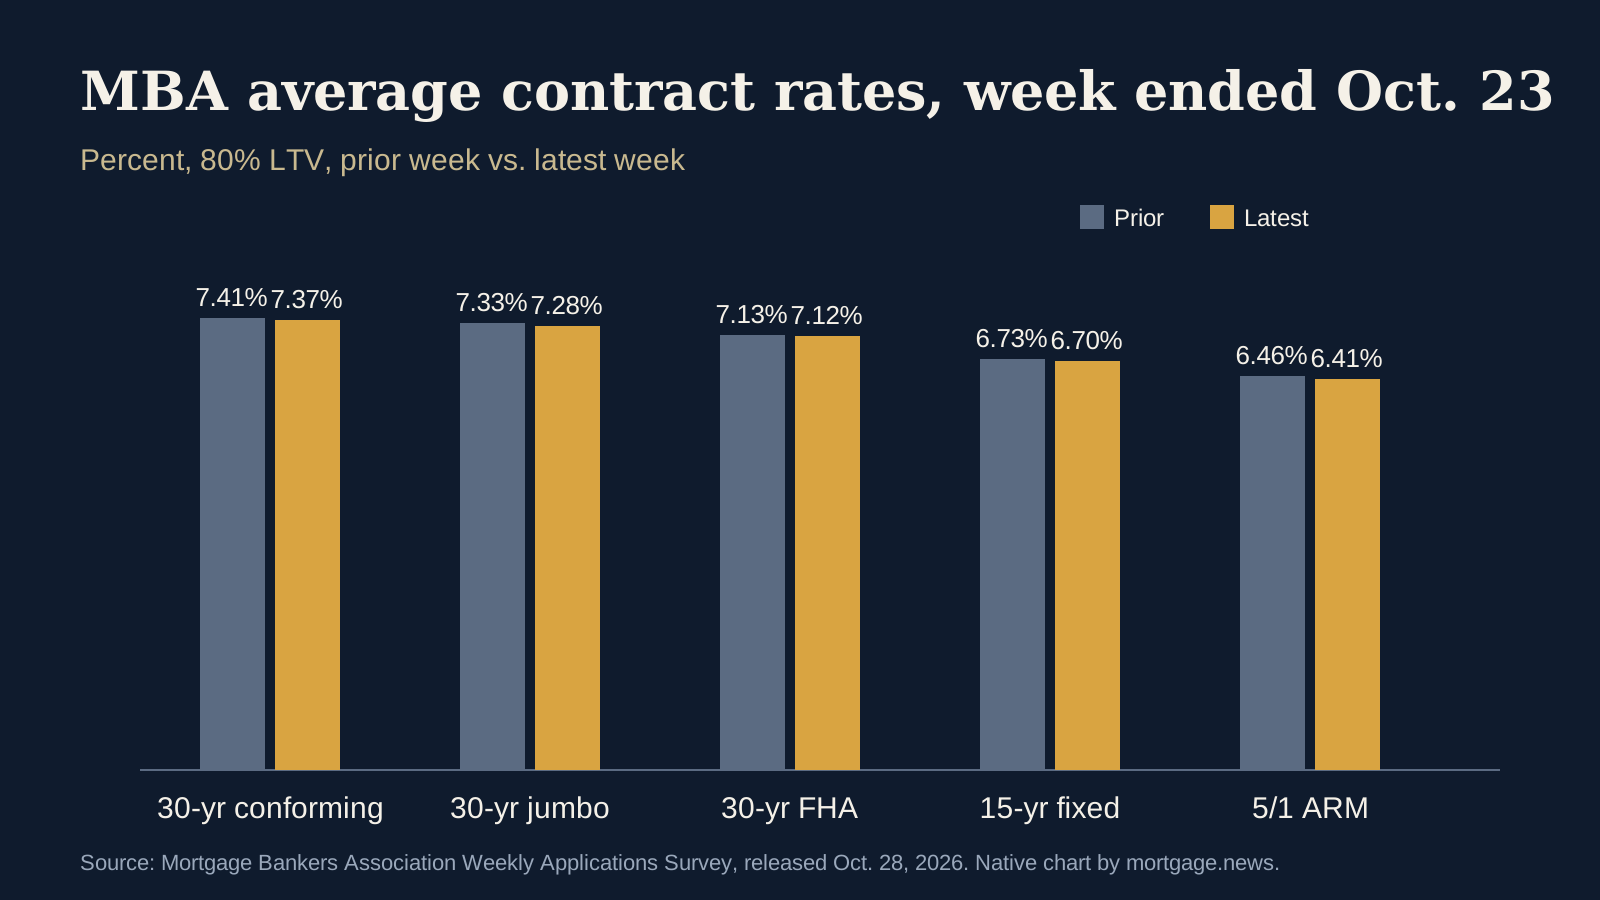
Mortgage applications rose 3.4% on a seasonally adjusted basis in the week ended Oct. 23, 2026, according to the Mortgage Bankers Association's Weekly Mortgage Applications Survey released Wednesday, Oct. 28. The gain followed a stretch of weekly declines and came as MBA's average 30-year conforming contract rate slipped to 7.37% from 7.41%.
The weekly bounce is real, but it is small next to last year's pace. MBA said unadjusted purchase applications were 18% lower than the same week a year earlier, and refinance applications were 61% lower.
What moved in the week
MBA's seasonally adjusted Purchase Index rose 4% from the prior week, and the Refinance Index rose 3%. On an unadjusted basis the composite index rose 3%. Refinances made up 38.9% of applications, down from 39.0%. The adjustable-rate share rose to 11.3%; MBA described this as the highest ARM share in more than a year.
Government lending shares were mixed. The FHA share rose to 16.6% from 16.3%, the VA share fell to 11.0% from 11.5%, and the USDA share held at 0.5%.
| Loan type | Prior week | Latest week | Points (prior to latest) |
|---|---|---|---|
| 30-year fixed, conforming ($832,750 or less) | 7.41% | 7.37% | 0.75 to 0.76 |
| 30-year fixed, jumbo | 7.33% | 7.28% | 0.60 to 0.64 |
| 30-year fixed, FHA | 7.13% | 7.12% | 1.15 to 1.07 |
| 15-year fixed | 6.73% | 6.70% | 0.73 to 0.85 |
| 5/1 ARM | 6.46% | 6.41% | 1.11 to 1.20 |
Source: MBA Weekly Mortgage Applications Survey, released Oct. 28, 2026. Points include the origination fee.
How to read MBA's rate
MBA's figure is an average contract rate reported by survey participants for loans with an 80% loan-to-value ratio, alongside the average points paid. It is not a quote any individual borrower will receive, and it differs from Freddie Mac's weekly Primary Mortgage Market Survey, which uses a different method and is published on Thursdays. Credit score, down payment, loan size, property type and the points a borrower chooses to pay all change the rate on an actual offer.
Points matter here. On conforming loans the rate fell four hundredths of a point while average points edged up to 0.76 from 0.75. A lower headline rate paired with higher upfront cost is not the same as cheaper borrowing for every household.
Period versus release date
The data cover applications taken during the week ended Friday, Oct. 23. They were published five days later. Anyone comparing this report with daily rate tables or other weekly surveys should line up the periods, not the release dates.
What MBA said
Joel Kan, MBA's vice president and deputy chief economist, said rates declined for a second straight week to the lowest level in three weeks and that the decline "gave borrowers some relief, with applications rebounding slightly, particularly conventional applications." He added that purchase activity remained 18% behind last year's pace and that most borrowers "have little to gain from refinancing" at current rates.
What borrowers and loan officers can do
Buyers can ask lenders for written Loan Estimates on the same day for the same loan amount and compare both rate and points. Homeowners weighing an ARM should look at how and when the rate can adjust, not only the starting rate. Loan officers can use MBA's numbers as market context while quoting from their own current pricing.
Source: Mortgage Bankers Association, "Mortgage Applications Increase in Latest MBA Weekly Survey," Oct. 28, 2026. Cover: native chart by mortgage.news from MBA's published contract rates.